The PNB case exposes weaknesses in financial oversight. India must make institutional accountability, not merely customer compensation, the cornerstone of banking reform.
A bank deposit represents far more than money. For millions of ordinary Indians, it is the product of decades of work, a family’s security and protection against an uncertain future. When that money disappears from a bank account, the damage extends beyond individual finances: it strikes at the public trust on which the entire banking system depends.
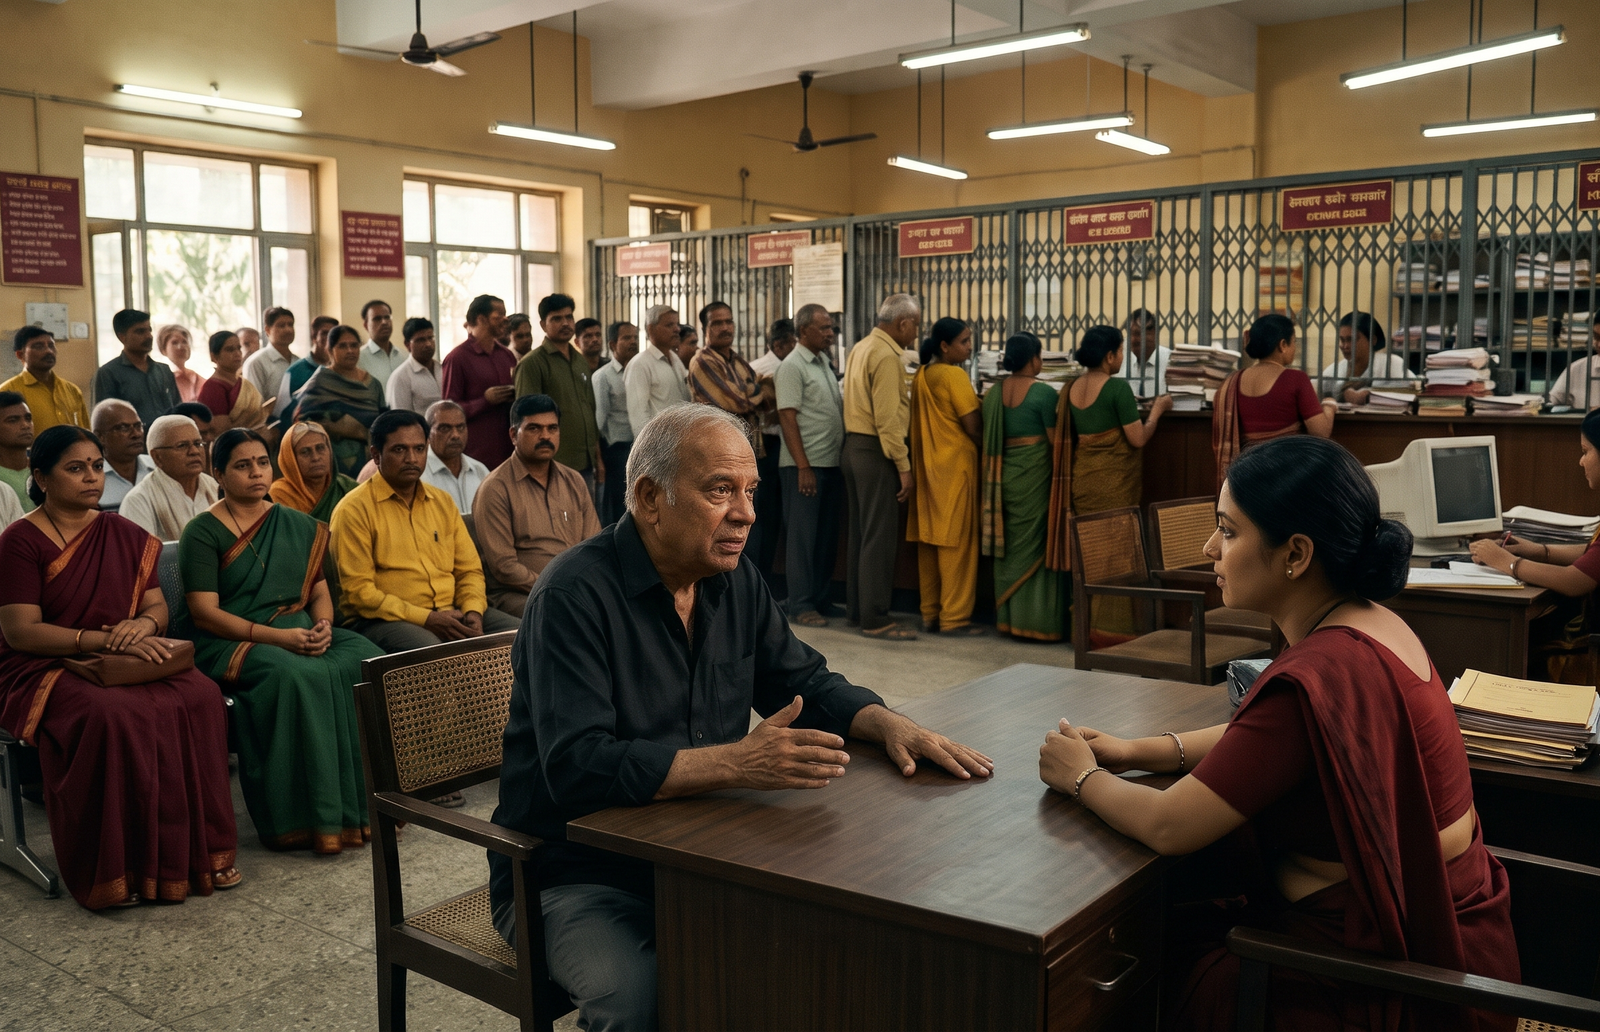
The alleged fraud at Punjab National Bank’s Greater Noida branch is therefore deeply troubling. Initial complaints from 21 account holders alleged losses exceeding ₹11.24 crore, while local estimates put the potential amount at around ₹35 crore. Subsequent reporting indicated that the bank’s assessment stood at approximately ₹10.24 crore, with the Central Bureau of Investigation (CBI) registering a case. The differing figures underline the need for a comprehensive, independent investigation. PNB has said it has settled three claims worth ₹43 lakh and will honour all genuine claims.
The crucial question is not simply how the alleged fraud occurred, but how it could allegedly persist for years without effective intervention. Reports suggest that employee credentials were misused and fixed deposits tampered with. If established, such findings would expose serious weaknesses in access controls, transaction monitoring and internal supervision.
India has witnessed major banking scandals before, including the fraud involving PNB and diamond trader Nirav Modi. Repeated incidents demand more than assurances of zero tolerance. They require evidence that safeguards work, suspicious transactions trigger immediate scrutiny and responsibility is traced through the institutional hierarchy.
The Reserve Bank of India (RBI) must ensure that regulatory standards translate into effective practice. Banks need independent audits, robust digital safeguards, separation of duties and alerts for unusual transactions. Senior executives must also be answerable when supervisory failures occur. Suspending junior employees may be necessary, but it cannot substitute for examining the decisions, systems and oversight that allowed misconduct to go undetected.
The same principle applies to large corporate lending. The Kingfisher Airlines episode raised enduring questions about credit assessment, risk management and the accountability of those approving substantial loans. Borrowers who default must face lawful recovery proceedings; equally, officials who knowingly disregard safeguards should face appropriate disciplinary or legal consequences. Accountability must not stop at the most convenient level.
There is, however, an important distinction between deposit insurance and compensation for alleged fraud. India’s Deposit Insurance and Credit Guarantee Corporation (DICGC) protects eligible deposits up to ₹5 lakh per depositor, per bank, including principal and interest. This cover applies in specified circumstances, such as bank liquidation or certain restrictions imposed by the RBI; it is not an automatic ₹5 lakh payout whenever money goes missing from an account.
For affected customers, especially families whose savings include compensation for acquired land, prolonged uncertainty can be devastating. In an increasingly digital economy, financial inclusion means little if people cannot trust institutions to safeguard their money. Public confidence is also essential to India’s ambitions for a stable, technology-driven financial system.
Where a bank is responsible for unauthorised losses, genuine claims must be resolved promptly under applicable law and established procedures. Investigations must be transparent, and negligent or culpable officials must face proportionate consequences.
The principle is simple: depositors should not bear the cost of failures they neither caused nor could reasonably prevent. A banking system earns public trust not through declarations of integrity, but by protecting ordinary people’s savings and holding those responsible for failures to account.
Author

Related Stories
Most Read
- 1Argentina’s ‘Vanishing Sea’: Rare Low Tide
- 2Effect of the 12 August 2026 Solar Eclipse on the 12 Zodiac Signs, Know Who Will Benefit and Who Will Have to Be Careful
- 3Powai: Minor Girl Sexually Assaulted by Six Men, All Accused Arrested Within 24 Hours
- 4HC finds peon’s dismissal over tea and biscuits amounted to ‘injustice’
- 5Brace for 29 June: a Capricorn Full Moon, Mercury retrograde and Jupiter’s leap into Leo